Senior Identity Theft: Protecting Personal Documents at Home
Identity theft is a serious risk for seniors. This guide offers practical, at-home strategies to secure personal documents and protect your loved one's identity.
When you think about keeping your aging parent safe, you probably picture preventing falls, managing medications, or ensuring they eat well. But there is another quiet threat that can cause tremendous financial and emotional damage: identity theft. For seniors, this crime is especially devastating because it can drain life savings, damage credit, and create a nightmare of paperwork to resolve. The good news is that many of the most effective prevention steps happen right at home, starting with how we handle personal documents. By taking a few proactive measures, you can build a strong defense around your loved one’s identity and give yourself peace of mind.
Why Seniors Are Vulnerable to Identity Theft
Seniors are often targeted by identity thieves because they may have substantial savings, home equity, and a lifetime of credit history. They might also be less familiar with digital scams or less likely to monitor their accounts regularly. Physical documents are a particular risk because many seniors keep important papers in easy-to-find places like a shoebox in the closet or a drawer in the kitchen.
Moreover, home care situations can bring a revolving door of visitors: home health aides, nurses, therapists, and even well-meaning neighbors. While the vast majority of these individuals are trustworthy, it only takes one person with bad intentions to access a Social Security card or bank statement. Additionally, seniors who receive a lot of mail, such as medical bills or insurance explanations, might accidentally leave them on the counter or in the trash, where someone can retrieve them.
The emotional toll is just as serious as the financial one. Victims of identity theft often feel violated, embarrassed, and overwhelmed. They may withdraw from family or become anxious about even routine transactions. For a senior who already feels vulnerable due to health issues, this can lead to depression or a loss of independence. Recognizing these risks is the first step toward protecting your loved one with compassion and practical action.
Start with a Document Inventory
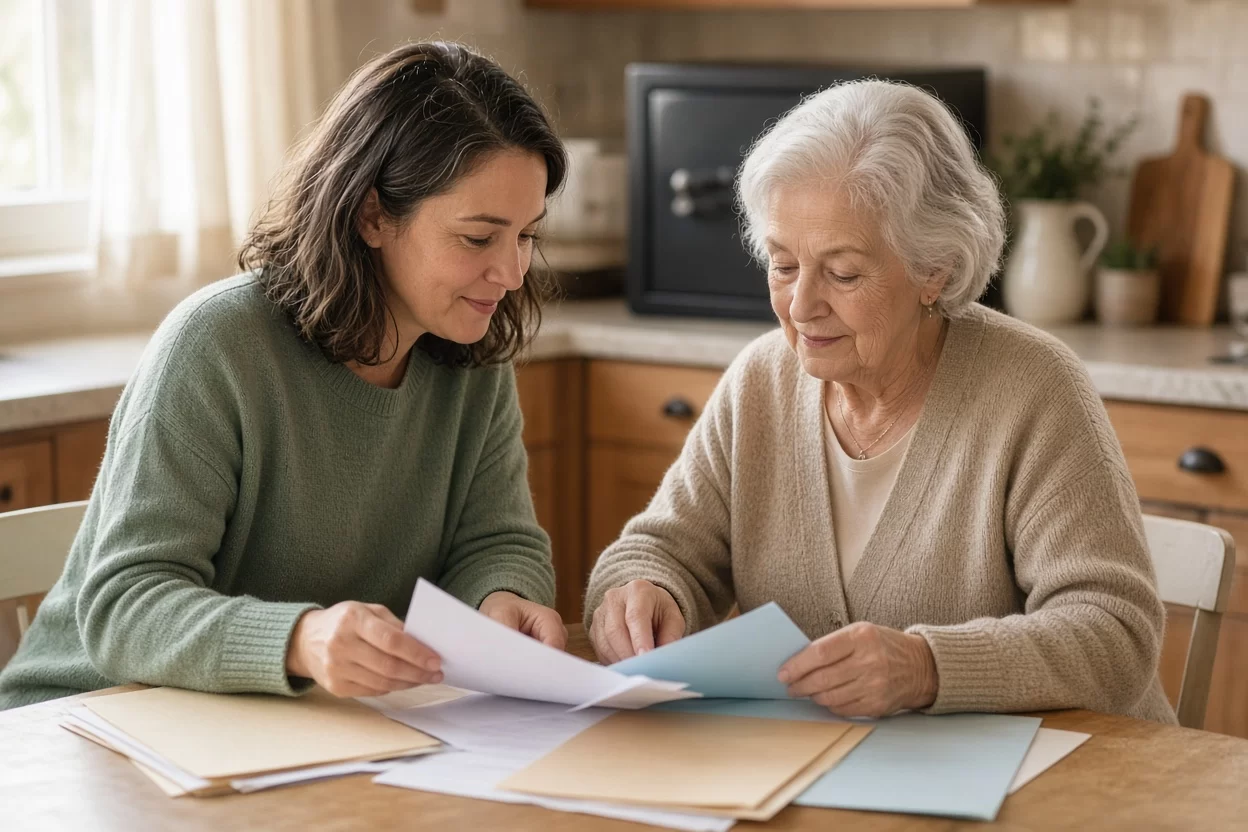
The foundation of home document security is knowing exactly what you have. Set aside a quiet afternoon to sit with your parent and go through their files, drawers, and any hiding spots. Create a simple list of every important document you find: Social Security card, Medicare card, passport, driver’s license, birth certificate, marriage certificate, property deeds, car titles, insurance policies, bank statements, tax returns, and investment account statements.
As you inventory, ask your parent if they have any documents stored outside the home, such as in a bank safe deposit box or with a trusted relative. Also, look for old documents that are no longer needed, like expired credit cards or paid-off loan papers. These should be shredded, not thrown away. You can rent a cross-cut shredder or find a local community shredding event. Make shredding a regular habit, at least once a month, to keep the pile manageable.
Once you have a full list, decide which documents are truly essential to keep at home. For example, your parent may not need to keep every bank statement from the last ten years. Financial institutions usually provide online statements, and you can download and save them digitally. For documents you do keep, create a single, secure location that is not obvious, such as a locked filing cabinet or a fireproof safe. Avoid labels like ‘Important Papers’ on the outside; a plain, nondescript box is better.
Secure the Social Security Card and Medicare Card
Your parent’s Social Security number is the master key to their identity. If a thief gets this number along with their name and date of birth, they can open credit cards, take out loans, or even file a fraudulent tax return. Therefore, the physical Social Security card should never be carried in a wallet or purse. It should stay in a locked safe or a secure document box at home.
Similarly, the Medicare card contains the beneficiary’s Medicare number, which is often the same as their Social Security number. While it is necessary to present the card at medical appointments, remind your parent to keep it in a safe place in their wallet, not in an open pocket. After each appointment, check that they have put it back. If your parent has a Medicare Advantage plan, they may have a separate card with a different number; still, treat it with the same level of care.
Consider making a photocopy of these cards and storing the copies in a secure location, but be aware that copies are just as sensitive as the originals. If the card is lost or stolen, report it immediately to the Social Security Administration and Medicare. Filing a police report can also help protect your parent’s rights and speed up the recovery process.
Create a Safe and Private Document Storage System
A dedicated, locked storage area is essential for protecting sensitive documents. A fireproof and waterproof safe is an excellent investment. Place the safe in a location that is not easily accessible to visitors, such as a bedroom closet or a home office. Choose a safe with a combination lock or a key that you, as the family caregiver, hold onto. If your parent has memory issues, they may not remember the combination, so you should have a backup plan.
Inside the safe, use labeled folders or envelopes for each category: identification, financial, medical, and legal. For example, one folder for bank and credit card statements, another for insurance policies, and a third for estate planning documents like wills and powers of attorney. Within each folder, keep the most recent documents on top. This system makes it easy to find what you need quickly, especially in an emergency.
Do not forget digital documents. If your parent has a computer or tablet, ensure that sensitive files are password-protected. Use a strong, unique password that you help them create, and consider enabling two-factor authentication on financial accounts. If they are not comfortable with technology, you can offer to manage online accounts with their permission, but always respect their privacy and keep them involved.
Manage Mail and Deliveries Carefully
Mail theft is a common way identity thieves obtain personal information. An unlocked mailbox outside the home is an open invitation. Encourage your parent to check the mail promptly every day. If they are physically unable to do so, you or a trusted neighbor should bring it in. Better yet, consider renting a locked mailbox at the post office or a private mail service, which adds a layer of security.
When reviewing the mail, look for any unexpected items, such as new credit card offers, collection letters, or statements from accounts you do not recognize. These could be signs of identity theft. Shred any pre-approved credit card offers before recycling them, as these can be used to open accounts in your parent’s name. If your parent receives a lot of junk mail, you can reduce it by opting out of prescreened credit offers at optoutprescreen.com.
If your parent is going on vacation or to the hospital, put a hold on their mail through the U.S. Postal Service. This prevents mail from piling up in the mailbox, which signals an empty house. Also, remind them never to leave outgoing mail with personal information in their own mailbox for the mail carrier to pick up; it is safer to drop it in a blue collection box or at the post office.
Monitor Financial Accounts and Credit Reports
Regular monitoring is one of the best ways to catch identity theft early. Help your parent set up online access to their bank, credit card, and investment accounts so you can review transactions together. Set a weekly or monthly routine to check for any unauthorized charges or withdrawals. Even small amounts can be a test by thieves before they attempt a larger theft.
You can also obtain a free credit report from each of the three major credit bureaus (Equifax, Experian, and TransUnion) once a year at annualcreditreport.com. Review the report carefully for any accounts you do not recognize or inquiries you did not initiate. If you find something suspicious, report it to the credit bureau and place a fraud alert on your parent’s credit file. A fraud alert makes it harder for thieves to open new accounts because creditors must verify the identity of the applicant.
Consider a credit freeze for your parent. A freeze blocks access to their credit report, making it nearly impossible for anyone to open new accounts without your permission. It does not affect their existing accounts, and it is free. You can lift the freeze temporarily when your parent applies for a loan or a new credit card. This is a powerful tool that gives you control over their credit.
Educate Your Loved One and Caregivers
Your parent may not understand the risks of identity theft, or they may be embarrassed to admit they do not know how to protect themselves. Have an open, patient conversation about the importance of keeping personal information private. Explain that they should never give their Social Security number, bank account details, or credit card numbers over the phone unless they initiated the call to a trusted number. Hang up on robocalls and be wary of callers claiming to be from the IRS or Medicare.
If your parent has a home health aide or other caregivers, make sure those individuals are properly vetted by the home care agency. Ask the agency about their background check process and training on client privacy. Remind your parent that they have the right to ask any caregiver to leave the room when they are handling sensitive documents. You can also create a ‘privacy rule’ where all personal paperwork is kept out of sight when a caregiver is present.
For seniors with dementia or cognitive decline, the challenge is greater. They may not remember to lock the safe or may accidentally share information with strangers. In such cases, you may need to take over the management of their finances and documents. A durable power of attorney allows you to act on their behalf, but you must use it responsibly and keep records of all transactions. Always involve your parent in decisions as much as possible to maintain their dignity.
What to Do If You Suspect Identity Theft
If you notice any signs of identity theft, act quickly. First, contact the fraud department of the company where the fraudulent activity occurred, such as a bank or credit card issuer. Close any compromised accounts and open new ones with new numbers. Then, place a fraud alert on your parent’s credit file by contacting one of the three credit bureaus; they will notify the other two.
File a report with your local police department. Bring a copy of the credit report and any evidence of the fraud. A police report is often required by financial institutions to dispute charges. Also, report the theft to the Federal Trade Commission at identitytheft.gov. This website provides a personalized recovery plan and helps you track your progress.
Finally, keep a detailed log of every call you make, every letter you send, and every person you speak to. This documentation will be invaluable if you need to dispute charges or restore your parent’s credit. Identity theft recovery can take months, so be patient and persistent. Remember that you are not alone; many resources are available to help you through the process.
Frequently Asked Questions
How often should I review my parent’s financial statements?
It is best to review bank and credit card statements at least once a month. This frequency allows you to catch unauthorized transactions quickly. For investment accounts, a quarterly review is usually sufficient, but you can check more often if you have concerns. Set a recurring reminder on your phone or calendar so you do not forget.
Is a credit freeze the same as a fraud alert?
No, they are different. A credit freeze blocks access to your credit report entirely, so no new accounts can be opened without a temporary lift. A fraud alert requires creditors to verify identity before opening a new account, but it does not block access. A freeze is the stronger protection and is recommended for seniors who are not planning to apply for credit soon.
What should I do with old documents that contain personal information?
Shred them with a cross-cut shredder. Do not simply throw them in the trash or recycling bin, as thieves can easily retrieve them. You can also use a professional shredding service, but make sure it is a reputable company. For documents you want to keep but not access often, consider scanning them to a secure digital format and storing the originals in a safe deposit box.
Can identity theft happen even if my parent never uses the internet?
Yes, absolutely. Identity theft can occur through stolen mail, discarded documents, or even a dishonest caregiver who accesses physical files. Thieves do not need the internet to use a stolen Social Security number. That is why securing physical documents and monitoring accounts is so important, regardless of your parent’s online activity.
How can I help my parent who has dementia protect their identity?
If your parent has dementia, they may not be able to manage their own documents or recognize scams. Take a proactive role by securing all sensitive documents in a safe that only you can access. Consider setting up automatic bill payments to avoid checks in the mail. Also, register them for the Do Not Call list and screen all phone calls. A legal power of attorney will allow you to handle their finances legally and ethically.
Protecting your aging loved one from identity theft is an act of love and vigilance. It may feel overwhelming at first, but you do not have to do it alone. Start with small steps, like securing one document at a time, and build from there. By creating a secure home environment, you are not just safeguarding their finances; you are preserving their peace of mind and independence.
If you need support in caring for your senior family member, our team at Rockaway Home Care is here to help. We offer compassionate, professional home care services that respect your loved one’s privacy and dignity. Reach out today for a free consultation to learn how we can assist you in creating a safe and secure home.
This information is for general guidance only and does not constitute medical or legal advice. Always consult with a qualified professional for specific concerns.
This article is general information, not medical advice. Please consult a qualified professional about your own situation.
More from the Rockaway Home Care blog
- Understanding Medicaid home care eligibility
- Top questions families ask about home care costs
- Choosing between live-in care and hourly home care
- How to create a home care plan for a loved one