When Your Parent Insists on Paying Cash: Protecting Their Savings
Many older adults prefer paying their caregiver in cash, but this can quietly expose savings to risk. Here is how families can respect their parent's wishes while protecting their financial security.
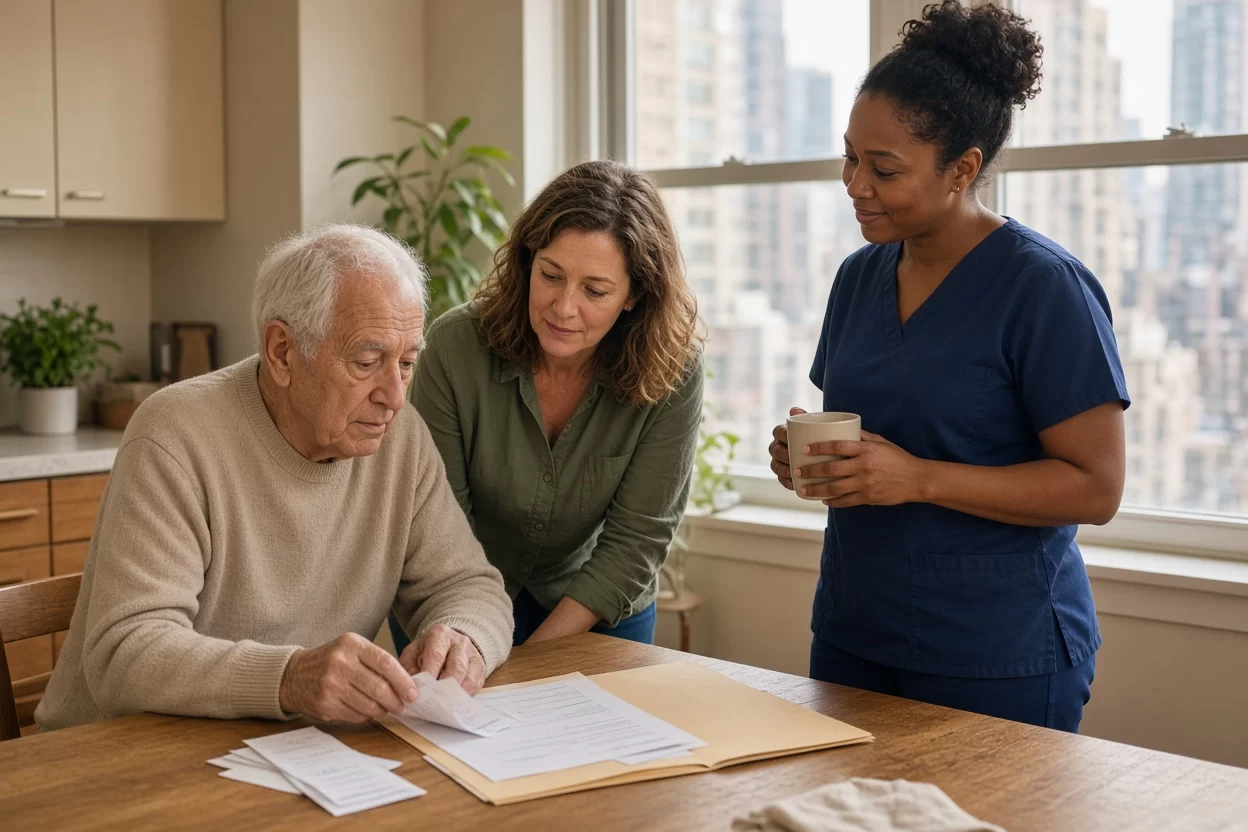
Maybe your mother has always handled her own money, and she simply does not trust checks, bank transfers, or anything she cannot hold in her hand. Perhaps your father is proud and wants to pay the caregiver himself each week, the way he always paid the plumber and the mechanic. When an aging parent insists on paying cash for home care, it can feel like you are pushing against their independence every time you raise the subject. Yet cash payments create real risks: no paper trail, no protection if a dispute arises, and more opportunity for money to disappear without anyone noticing. This guide is meant to help you honor your parent’s dignity while putting sensible safeguards around their savings.
Why Older Adults Often Prefer Cash
Before you can address the habit, it helps to understand where it comes from. Many people in their seventies, eighties, and nineties grew up in a time when cash was the normal way to settle a bill, and writing a check or using an app may feel unfamiliar or even suspicious. Some have lived through bank failures, identity scares, or stories of online fraud and would rather keep control in their own hands. Others simply find it easier to count out bills at the kitchen table than to log into an account on a screen that keeps changing.
There can also be emotional reasons. Paying in cash may make your parent feel like the head of the household again, not someone being looked after. It can be a way of saying, I am still capable, I still make my own decisions, and I am not a burden. Recognizing this helps you approach the conversation with empathy rather than frustration.
- Cash feels immediate and under their personal control.
- Older habits and generational comfort with paper money.
- Distrust of banks, apps, or electronic payments after hearing about scams.
- A desire to maintain pride, autonomy, and a sense of usefulness.
- Confusion about how other payment methods work.
The Real Risks Behind Cash Payments
Cash is convenient in the moment, but it creates several vulnerabilities that families often do not notice until a problem appears. The most obvious is that cash leaves no record. If your parent pays two hundred dollars on Friday and believes they paid it on Thursday, there is nothing to resolve the question. If a caregiver later claims a payment was missed, your parent may have no proof either way, and the disagreement can damage the relationship and cause real stress.
Cash also makes theft easier to hide. Money kept in a drawer, a purse, or an envelope can be taken by someone with access to the home, and the loss may not be discovered for weeks or months. Older adults who are experiencing early memory changes may also lose track of how much they have withdrawn, paid out, or spent, which can make it hard to tell whether money is missing or simply forgotten.
Finally, large or frequent cash withdrawals can draw attention from bank staff, and in some cases they may become a warning sign of financial exploitation. A family member, neighbor, or new acquaintance may push an older adult to withdraw cash regularly. Knowing the patterns of your parent’s spending can help you spot changes early.
Signs That Cash Handling Needs Attention
- Repeated requests for large cash withdrawals with unclear purpose.
- Your parent says money is missing, or cannot account for what was paid.
- Unexplained gaps between how much cash was withdrawn and what was spent.
- New people who suddenly seem very involved in handling their money.
- Bills going unpaid while cash seems to disappear.
Start With a Respectful Conversation
Changing how money is handled works best when it feels like a shared decision rather than an order from the family. Try to begin the conversation when things are calm, not during a crisis or right after a missed payment. Ask your parent what matters most to them about how they pay. Is it being able to see the money leave their hands? Is it avoiding bank fees? Is it trusting the person they pay? Their answers will tell you which concerns to address first.
Frame your concerns around protecting them rather than doubting them. For example, you might say something like, I want to make sure that if anyone ever questions a payment, you have a record that proves you paid on time. This keeps the focus on their security and their good name. Avoid language that implies they cannot manage their own affairs, even if you have started to worry about memory or judgment.
It also helps to involve the caregiver or agency in these conversations, so your parent understands that a clear record is standard and protects everyone. Most reputable home care arrangements already include documentation of services and payments, and seeing that as normal rather than suspicious can make the transition easier.
Practical Options That Keep Cash Feeling Familiar
You do not have to switch your parent to a completely unfamiliar system overnight. Many families find success with a middle path that keeps some of the comfort of cash while adding a paper trail. One approach is to have your parent continue paying in cash, but always obtain a signed, dated receipt that lists the amount, the date, the service period, and the names of both parties. The receipt should be kept in a designated folder that a trusted family member can review.
Another option is to withdraw a set amount of cash on a regular schedule, such as once a week, and record each withdrawal in a simple log. This limits how much cash is in the home at any one time and makes it easier to see whether money is unaccounted for. A small notebook kept near the cash envelope, with columns for date, amount, what it was for, and initials, can work well for many families.
Consider Gradual Changes
If your parent is open to it, you might suggest a gradual move toward traceable payment methods. A check is often a comfortable first step, since it is paper, it can be held and signed, and it creates a bank record. Some families then move toward automatic bill pay through the bank, which many older adults find reassuring once they understand that they still control the account. Taking small steps over several months tends to be more successful than a sudden change.
- Signed, dated receipts for every cash payment.
- A simple written log of withdrawals and payments.
- Paying by check so there is a bank record.
- Automatic bill pay set up with your parent’s full agreement.
- Keeping only a modest amount of cash in the home.
Keeping Good Records Without Feeling Watched
Good record keeping protects everyone, including the caregiver, but it does not have to feel like surveillance. The goal is a clear, shared document that answers basic questions: how much was paid, when, for what period, and by whom. When records are kept openly and reviewed together, they become a source of reassurance rather than suspicion.
A practical system might include a one-page monthly summary that lists each payment, the receipt number, and the total for the month. Your parent can keep a copy, and so can a designated family member or the person who helps with their finances. Storing paper records in one labeled binder in a consistent place reduces the chance that receipts get lost or thrown away during cleaning.
If your family uses a home care agency, ask what records the agency provides for services and payments. Clear invoices and service logs can supplement the receipts your parent keeps, so that both sides have a matching account of what was delivered and paid. Reviewing these together once a month can catch small discrepancies early, before they grow into bigger misunderstandings.
Protecting Against Exploitation and Theft
Even with the best intentions, older adults can become targets for people who want their money. Watch for caregivers or visitors who ask for extra cash for things that were never agreed upon, who discourage family involvement, or who seem to have a sudden interest in your parent’s bank accounts. Be especially alert if money is requested for emergencies, gifts, or loans, and if your parent becomes secretive about where their money goes.
Physical security matters too. Keep cash in a locked box or a secure location that is not obvious, and limit how many people know where it is kept. Consider whether a home safe, bolted to the floor, would make sense. Make sure your parent knows they can say no to any request for money that makes them uneasy, and that they can always talk with you first.
If you suspect theft or exploitation, act promptly. Document what you have noticed, speak with your parent privately, and contact the bank if unusual withdrawals are involved. In New York, concerns about abuse or financial exploitation of an older adult can be reported to Adult Protective Services, and local law enforcement can help if a crime may have occurred. Acting quickly protects both your parent and the people who care for them.
Questions to Ask Before Hiring or Continuing Care
- Does the agency or caregiver provide written receipts or invoices?
- What is the process if a payment is disputed?
- Who else in the household or agency will know about payment arrangements?
- Are there background checks and supervision in place?
Involving Family Without Taking Over
Many families struggle with the balance between helping and controlling. You want to protect your parent’s savings, but you also want them to feel respected and in charge of their life. One helpful way to approach this is to agree together on a small number of protections, such as receipts and a monthly review, and leave the rest of the decisions to your parent. Ask them to explain how they like to handle things, and try to build on those habits rather than replacing them.
If several siblings or relatives are involved, decide early who will review the records and how often. Share the responsibility so that one person is not carrying all the worry. Keep the family conversation focused on your parent’s wellbeing and wishes, and avoid turning money discussions into arguments about who has done more. A calm, regular check-in often works better than sporadic, stressful audits.
Consider whether a formal legal arrangement makes sense over time. A durable power of attorney or a trusted-person designation can allow a family member to help with finances if your parent later loses capacity, but these documents should be prepared with a qualified attorney while your parent is still able to make their own choices. Planning ahead, with your parent’s full participation, is far kinder than making emergency decisions later.
When Memory or Judgment Changes
If you notice that your parent is repeating questions, losing track of bills, or making unusual decisions about money, it is important to talk with their doctor. Changes in memory or judgment can have many causes, some of which are treatable, and an evaluation can help the family understand what support is needed. Early attention also gives your parent more opportunity to take part in planning for their future.
As needs change, the approach to cash may also need to change. A parent who once handled every payment may now benefit from a simpler system with fewer steps, more automation, and greater oversight. This shift does not have to erase their role. You can still ask for their opinion, let them choose between options, and celebrate the decisions they continue to make, even as the family takes on more of the practical work.
Frequently Asked Questions
Is it wrong for my parent to pay their caregiver in cash?
Paying in cash is not automatically wrong, and many families do it without any problems. The concern is the lack of a record, which can make it hard to prove payments were made or resolve disagreements. Adding receipts and a simple log usually addresses most of the risk while keeping the comfort of cash.
My parent gets upset when I ask about their money. What should I do?
Try to approach the conversation gently, focusing on their security and their wishes rather than on doubts about their ability. Choose a calm moment, ask them what matters most to them, and let them help design the system. If the resistance continues or is paired with other concerns, consider involving their doctor or a trusted elder law professional for support.
How often should someone review cash payments and receipts?
Many families find that a monthly review works well, with a quick check each week if cash is handled frequently. The right schedule depends on how much money is involved and how much support your parent needs. Whatever rhythm you choose, keep it consistent so that problems are caught early.
What should I do if I think money is being stolen?
Document what you have observed, including dates and amounts, and speak with your parent privately about your concerns. Contact their bank to review unusual activity and consider reporting to Adult Protective Services in New York if you believe an older adult is being financially exploited. If a crime may have occurred, local law enforcement can advise on next steps.
Can a caregiver ask my parent for extra money or gifts?
Caregivers should not ask for loans, gifts, or extra payments beyond what was agreed upon, and families should be alert to any such requests. Make clear to your parent that they are never obligated to give extra money and can always check with you first. Reputable agencies typically have policies that prohibit these arrangements and provide a way to raise concerns.
Caring for a parent means caring for their dignity as well as their safety, and the question of how they pay for help touches both. When you approach the topic with patience, clear records, and a willingness to listen, you can protect their savings while still honoring the independence that matters so much to them. If you are unsure where to start, Rockaway Home Care welcomes the chance to talk through your situation and explain how our documentation and billing practices work. Reach out for a free consultation, and let us help your family find an approach that feels respectful, transparent, and secure.
This article is general information, not medical advice. Please consult your parent’s physician, a qualified financial professional, or an elder law attorney for guidance specific to your family’s situation.
More from the Rockaway Home Care blog
- Understanding Medicaid home care eligibility
- Top questions families ask about home care costs
- Choosing between live-in care and hourly home care
- How to create a home care plan for a loved one