When Your Parent Starts Mailing Checks to Strangers
Discovering that a parent has been mailing checks to people they barely know is frightening and confusing. This guide explains the warning signs, the reasons behind it, and the practical steps families can take right away.
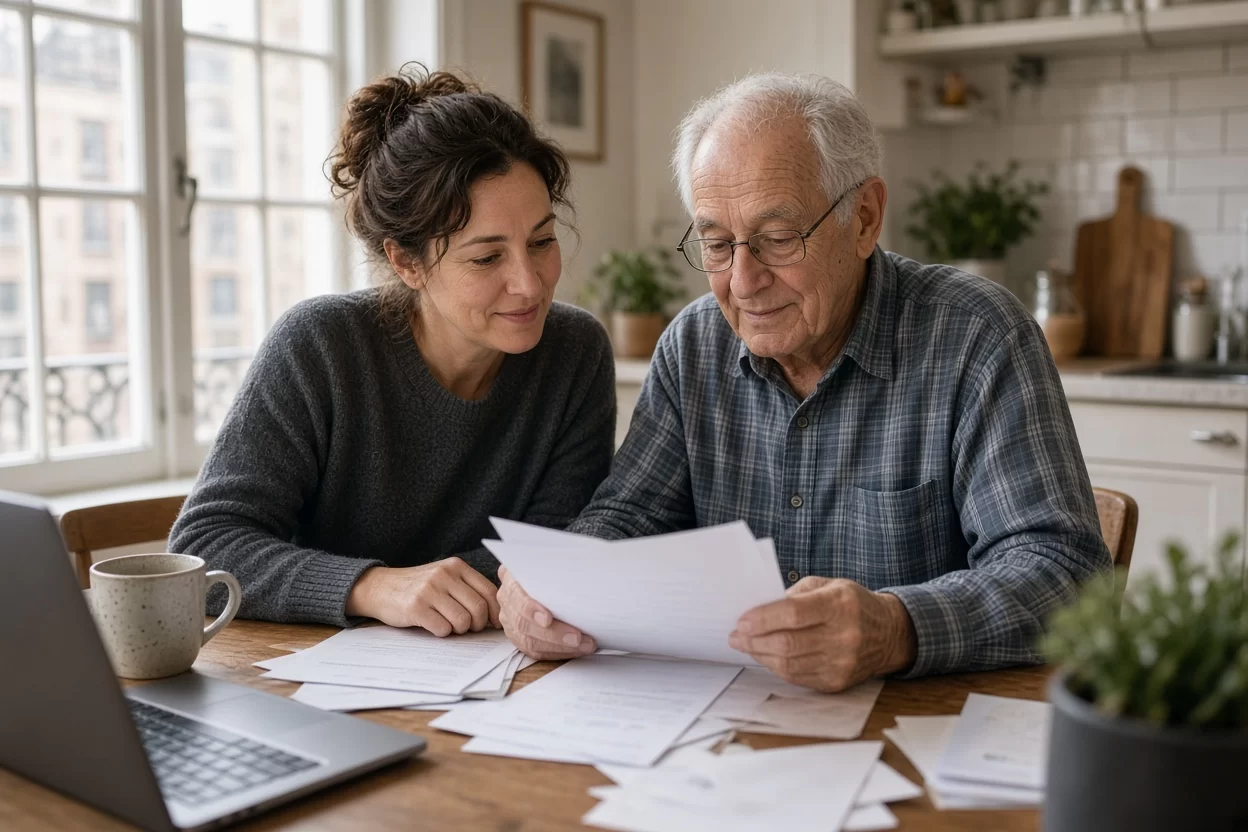
Finding out that your mother or father has been mailing checks to people you have never heard of can stop your heart for a moment. Maybe you noticed a missing checkbook, a bank statement with unfamiliar payees, or a neighbor who mentioned a letter asking for money. Whatever the discovery looked like, the feeling is usually the same: shock, worry, and a painful question about what is happening to the person you love. This article walks through why it happens, what warning signs to look for, and how to protect your parent without stripping away their dignity.
Why Older Adults Mail Money to Strangers
Sending checks to strangers is rarely a single bad decision. Often it is the result of a pattern that builds over weeks or months. Many scammers target older adults through sweepstakes notices, fake prize letters, romance schemes, grandparent scams, and phony charity appeals. These messages are designed to create urgency and emotion, and they are written to sound official, warm, or desperate depending on what will work best on the reader.
Cognitive changes can make a person more vulnerable. Memory loss, reduced judgment, or confusion can make it harder to recognize that a request is suspicious or to remember that a payment was already sent. Some people with early dementia will feel strongly that they owe a debt to a caller or that a letter must be answered quickly. Others are simply lonely, and a letter or phone call from someone who seems friendly can feel like companionship. Loneliness and isolation are real risk factors, and they deserve compassion rather than blame.
It is also important to understand that intelligence and education do not protect anyone. Fraud schemes are professionally designed, and many of the people who fall for them are sharp, capable adults who simply encountered a convincing story at a vulnerable moment. Framing the problem as a skill failure can make your parent feel ashamed and less willing to talk with you. Framing it as a sophisticated trick that targets many good people tends to open the door to honest conversation.
Common scam types to be aware of
- Prize or sweepstakes letters asking for a fee or tax payment before a prize can be released
- Grandparent scams, where a caller pretends to be a grandchild in trouble and needs money wired or mailed immediately
- Romance or friendship scams, where a new contact builds trust over time and then asks for money for a crisis
- Fake charity or disaster appeals that use emotional language and urgent deadlines
- Government or utility impersonation, where a caller claims a bill is overdue or a benefit is at risk
- Check overpayment schemes, where your parent is asked to return a portion of a check that was never valid
Warning Signs Families Often Miss
Most families do not notice this problem until a significant amount of money is gone. Learning the early warning signs gives you a chance to step in sooner. Pay attention to changes in mail volume, especially envelopes with official-looking return addresses, bulk mail from unfamiliar organizations, or letters that arrive with prize language on the front. A sudden stack of mail that your parent guards or keeps out of sight is worth noticing.
Changes in banking behavior can be even more telling. Look for new checks ordered, a checkbook that is always missing, withdrawals that seem unusual for your parent, or a balance that drops faster than expected. Some older adults begin writing checks to people they describe as friends, advisors, or new acquaintances, and they may become defensive when asked about them. Secrecy, irritability when money is discussed, and sudden anxiety about deadlines are all signals that deserve a gentle follow-up.
Emotional and behavioral changes can appear alongside financial ones. A parent who seems unusually excited about a windfall, who talks about a new relationship they have never introduced you to, or who appears frightened or rushed when on the phone may be under pressure from a scammer. Keep in mind that some of these changes may also reflect depression, medication effects, or a medical condition that needs evaluation, so a conversation with your parent’s doctor is a reasonable next step.
A quick checklist for family members
- Review recent bank and credit card statements for unfamiliar payees
- Ask whether any new checks, money orders, or gift cards have been purchased
- Look through incoming mail for prize notices, urgent payment requests, or charity appeals
- Notice whether your parent has begun speaking about a new friend or advisor you do not know
- Check whether your parent is isolating, hiding mail, or refusing help with finances
How to Talk With Your Parent Without Causing Shame
The conversation you have with your parent can make the difference between a productive discussion and a defensive standoff. Start from a place of curiosity and care rather than accusation. Instead of saying you found out they have been sending money to strangers, you might say you noticed some checks you did not recognize and you want to make sure everything is okay. Ask questions, listen to the answers, and avoid lecturing.
Choose a private, calm moment rather than a rushed one in public or during an argument. Sit together, perhaps over coffee, and speak in terms of shared concern. Acknowledge that scams are designed to fool smart people and that you want to protect them from the emotional and financial harm these schemes cause. Many parents respond better when they feel respected and included in the solution rather than managed by their children.
Be prepared for denial or anger. A parent may insist the payments are legitimate, that the new friend is trustworthy, or that you are overreacting. You do not have to win the argument in one conversation. Your goal in the first talk is to open a door, not close the case. Suggest that the two of you check the details together, perhaps by calling the organization using a number you find yourself rather than one listed in the letter, and let the facts speak over time.
Phrases that tend to help
- I care about you and I want to make sure you are safe with your money
- Scammers are very good at this, and it happens to many capable people
- Can we look at this together so I understand what is going on
- You do not have to decide anything today, let us take it one step at a time
Practical Steps to Stop Payments Right Away
Once you have a clearer picture, act quickly to limit the damage. Contact your parent’s bank as soon as possible. Ask whether the bank can flag unusual check activity, place a hold on certain payees, or add a second authorized contact to the account. Many banks offer alerts for large or unusual transactions, and some will work with families to set up additional safeguards. Ask whether a checkbook can be temporarily stopped or whether checks can be limited for a period while the situation is reviewed.
Consider placing stop-payment orders on any checks that have not yet cleared, and request that the bank monitor the account for recurring payments to the same recipients. If you have legal authority through a power of attorney or guardianship, your role may make these steps easier. If you do not, talk with the bank about what options exist, since rules differ and some protections require the account holder’s consent.
Limit the flow of solicitations. You can ask your parent to add their phone number to national do-not-call registries, reduce unsolicited mail by opting out through reputable channels, and ask their bank and mail carrier about options for flagging suspicious mail. If your parent is receiving a high volume of solicitation letters, a trusted family member can help sort mail on a regular schedule.
Immediate actions
- Call the bank and ask about stop payments, transaction alerts, and account safeguards
- Document every suspicious check, payee, and letter, including dates and amounts
- Report suspected fraud to appropriate authorities, such as local police and the consumer protection agencies in your state and at the federal level
- Consider reporting elder financial exploitation through your local Adult Protective Services office if you believe your parent is at ongoing risk
- Keep copies of everything in a folder so you can share details with banks, doctors, or investigators
Protecting Your Parent’s Future Finances
Stopping the current payments is only part of the solution. Longer-term protection usually involves building a structure around your parent’s money that makes it harder for scammers to reach it. This may include a durable power of attorney that names a trusted person to manage finances if your parent becomes unable to do so, and a conversation with an elder law attorney about whether other planning tools are appropriate. These steps are most effective when done while your parent is still able to participate in the decisions.
Many families find it helpful to set up automatic bill payments for recurring expenses, so fewer checks need to be written by hand. Reducing the number of open checks, moving to a single account for daily bills, or using a debit card with clear transaction history can also make suspicious activity easier to spot. Some families choose to have a trusted family member or professional receive a copy of the monthly statement so irregularities are caught early.
Consider the role of professional support. Home care aides who visit regularly can help notice changes in mail, routines, and mood, and they can alert family members to concerns. Care managers and social workers can help coordinate medical evaluations, check on cognitive health, and connect families with community resources. Support for the caregiver matters as well, since managing a parent’s finances while also working and caring for a household can be exhausting.
When Cognitive Decline May Be Involved
If your parent is showing signs of memory loss, confusion, or changes in judgment, it is important to ask whether a medical evaluation is needed. Sudden changes in financial behavior can sometimes be an early sign of a condition that affects decision-making, and identifying the cause can lead to treatment and to better planning. A primary care provider can start the conversation and refer your parent to specialists if needed.
When cognitive changes are present, the goal shifts toward safeguarding decisions while preserving as much independence and dignity as possible. Families often find that clear routines, simplified finances, trusted helpers, and regular check-ins make daily life safer without removing choice entirely. Involve your parent in planning wherever they are able, and explain changes in simple, respectful language.
It may also be appropriate to talk with an elder law attorney about options such as guardianship, though this step is significant and generally considered only when less restrictive approaches are not enough. Many families start with voluntary arrangements, such as a durable power of attorney and account safeguards, and reserve more formal steps for situations where a parent is at serious ongoing risk.
Taking Care of Yourself as the Family Caregiver
Discovering a financial problem with a parent can leave you feeling angry, guilty, and exhausted all at once. You may wonder why you did not notice sooner or whether you failed your parent. Try to be gentle with yourself. Scams are designed to hide, and the people who run them are skilled at making their requests look normal. Noticing the problem now, and taking steps to address it, is an act of care.
Build a small support system. Talk with other family members, a trusted friend, a faith leader, or a caregiver support group. Share the workload of checking mail and statements, and set clear boundaries about what you can and cannot take on. If you feel overwhelmed, consider asking a professional care manager to help coordinate the many moving parts of your parent’s care and finances.
Frequently Asked Questions
What should I do first if I find out my parent has been mailing checks to strangers?
Start by calling your parent’s bank to ask about stop payments and account safeguards, and gather copies of any checks, letters, and statements you can find. Try to have a calm, private conversation with your parent to understand what is happening without shaming them. Consider reporting the activity to local police and to Adult Protective Services if you believe the exploitation is ongoing.
Can the bank stop my parent from writing checks?
Banks have different tools and policies, and the options available depend on the account type and on whether you hold any legal authority, such as a power of attorney. Many banks can place stop-payment orders, flag unusual activity, or add additional safeguards with the account holder’s agreement. Ask your parent’s branch about what is possible in their specific situation.
My parent says the people they are paying are their friends. What should I do?
Try not to argue directly about whether the person is a friend, since that often increases defensiveness. Instead, ask gentle questions about how they met, what the money is for, and whether they have ever met in person. Encourage your parent to check any requests with you or another trusted person before sending money, and consider reporting the contact to the appropriate authorities if you have concerns.
Is this a sign my parent has dementia?
Not necessarily, since many people fall for scams with no cognitive impairment at all. However, sudden changes in financial judgment can sometimes be an early sign of a medical condition, so it is reasonable to ask your parent’s doctor for an evaluation. A medical review can identify treatable causes, such as medication effects or infections, and can guide future planning.
How can I protect my parent going forward without taking away their independence?
Focus on layered safeguards, such as transaction alerts, automatic bill payments, fewer open checks, and a trusted person who reviews statements regularly. Involve your parent in decisions as much as possible and explain each step in respectful terms. Consider a durable power of attorney and a consultation with an elder law attorney while your parent can still take part in those choices.
If you are worried about your parent and feel unsure where to begin, you do not have to face this alone. Rockaway Home Care is glad to talk with families who are navigating these concerns, including questions about in-home support, caregiver assistance, and ways to keep a loved one safe at home. We would be honored to offer a free consultation to help you think through your options and next steps. Reaching out is a meaningful first step, and our team is here to listen.
note that this is general information, not medical advice
More from the Rockaway Home Care blog
- Understanding Medicaid home care eligibility
- Top questions families ask about home care costs
- Choosing between live-in care and hourly home care
- How to create a home care plan for a loved one